 11

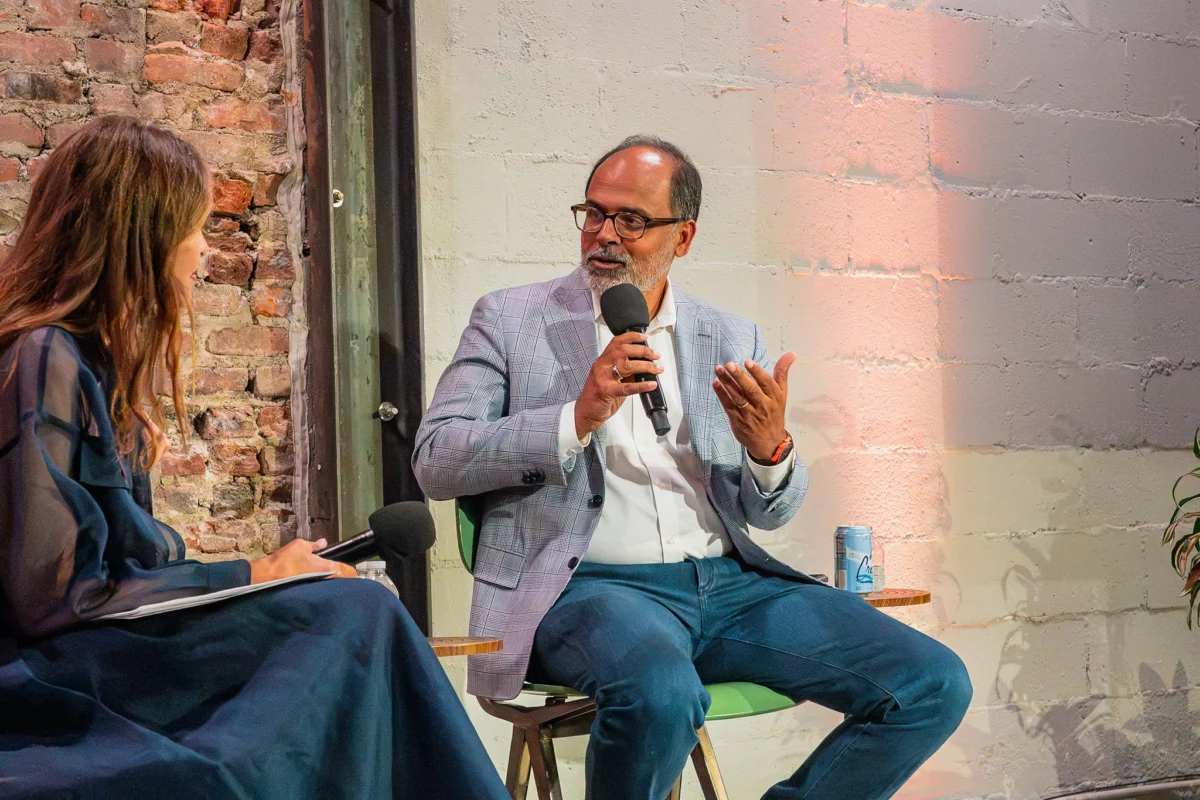
Parekh offered refreshing insights into the firm’s investment philosophy, its significant wins—such as leading and co-leading numerous rounds in Databricks and holding stakes in OpenAI and Anthropic—and the deals that eluded them, including the buzzy AI legal-tech company Legora. He also delved into the complexities of conflicts of interest in venture investing and articulated why Insight has steadfastly adhered to a diversified strategy, even as many VCs have concentrated their focus on frontier AI labs. The following is an edited transcript of the interview, offering a comprehensive look into the mind of one of venture capital’s long-standing leaders.
Navigating AI: Risks, Rewards, and a Confident Bet
Addressing concerns about AI risk, particularly in the wake of a researcher’s public warnings, Parekh dismissed the notion that such worries amount to hysteria, acknowledging real risks while maintaining a profoundly optimistic outlook. "Sure, there’s a risk some non-state actor gets access to an open-source model and creates a biological weapon," he conceded. However, he immediately countered this by highlighting a "higher probability we get a massive decrease in the time it takes to develop new drugs and cure diseases." For Parekh, this is a bet he is willing to take.
He provided tangible examples of AI’s current positive impact, drawing from his experience on the board of NYU Langone. "What AI is already doing with patient data is amazing," he noted. "We can look at 50 million patient records and tell someone walking in for something unrelated that they have a 25% chance of a heart attack." For Parekh, the net effect of AI is "highly positive." He framed AI risks as part of an ongoing historical pattern of technological advancement, akin to "next-generation drone warfare." He believes that while "every generation has new risks," living standards continue to rise. Crucially, he emphasized AI’s necessity in scaling healthcare, particularly given an aging global population and a shortage of medical professionals.
Insight’s Deliberate Discretion: "Let the Portfolio Do the Talking"
With $90 billion in assets under management, Insight Partners stands as a giant in the investment world, yet it maintains a comparatively quiet public presence. Parekh confirmed this is a deliberate strategy. He critiqued the trend of many venture capitalists who "think they’re an expert on everything now – epidemiology during COVID, geopolitics during the Iran war." He questioned this pervasive expertise, stating, "I’m not sure we’re all experts on everything."
Insight’s philosophy, by contrast, is straightforward: "Our attitude has been: Let the portfolio do the talking." The firm’s focus remains on "investing in founders and companies." While acknowledging the need for sufficient communication to ensure brand recognition, Parekh firmly believes that "our performance should speak for itself – and that’s driven by the portfolio, not by us being loud."
A Flexible and Diversified Investment Mandate
Insight Partners employs a broad investment strategy, spanning early-stage ventures, growth equity, buyouts, and secondaries. Parekh explained that the allocation across these stages is "temporal, not fixed," with no rigid geographic or strategic percentages. Examining their last seven funds reveals varying proportions of early-stage, growth, and buyout investments in each.
Current market conditions significantly influence this allocation. Parekh observed that "buyouts aren’t great right now – rates are high, debt markets aren’t receptive to software, exit multiples have come down." Consequently, Insight hasn’t executed a major buyout since 2024.
On the venture side, a different challenge has emerged: "valuations are rising at a pace we saw before, in 2021 – and that didn’t end well." He highlighted a critical issue where rounds move so quickly that "there’s almost no incremental data, so you’re paying more without reducing risk." The logical response, he noted, is to "go earlier." With a "scale fund" like Insight, this means the flexibility to make smaller initial bets—such as a "$20–25 million check instead of $500 million"—and then "double down on the winners." He underscored that a disproportionate share of their returns has historically come from this strategy. The example of Wiz was cited: "we wrote a Series A and kept writing checks, so our gain was much larger than if we’d stopped at the first check. And if Wiz hadn’t worked out, it would have barely dented a fund our size."
Geographic Dispersion and the AI Concentration Anomaly
While Parekh noted that "talent has gone flat globally," leading Insight to compete for deals like Legora in Stockholm (which they lost to General Catalyst), he identified a significant exception. "AI infrastructure talent is genuinely concentrated in San Francisco," he observed. This concentration is so pronounced that his 23-year-old son, also a VC, is relocating there, believing "you can’t invest in AI without being there." However, Parekh clarified that talent density varies by vertical, citing Ramp in New York as an example of financial services talent concentration. This allows for more geographically diverse investments in "vertical AI" compared to pure AI infrastructure.
Regarding the loss of Legora to General Catalyst, Parekh was pragmatic: "I don’t know the specific reason, but I think they sold their value proposition better than we sold ours that time." He quickly added, "There are plenty of examples where it went the other way. It’s a big world; we don’t need to win every deal."
Navigating Conflicts of Interest: OpenAI and Anthropic
Insight Partners’ investments in rival companies like OpenAI and Anthropic—a practice once considered taboo in venture capital—prompted questions about internal anguish and potential perceptions from founders. Parekh revealed that the internal debate centered more on "whether we should have gotten into earlier rounds." He emphasized that the issue is "very stage-dependent." He explained that an early-stage investor like Khosla, having led OpenAI’s Series A, could not then invest in Anthropic, and vice-versa for an Anthropic Series A investor.
However, once a firm invests at a "later stage, off the board, not driving governance," the investment is viewed as simply "buying a great stock." Parekh clarified their rationale: "We saw OpenAI as the dominant consumer play and Anthropic as having a clear enterprise strategy; that’s shifting in real time." He also pointed out that as these companies sought to raise massive amounts of capital ($30–100 billion), "they stopped being able to dictate exclusivity." At the Series A/B stage, Insight maintains "information-sharing restrictions" and avoids investing in "directly competing companies," though he acknowledged some founders’ sensitivity even to minimal revenue overlap.
Cautious Approach to Physical AI
When asked about increasing aggression in physical AI investments, Parekh described these companies as "still largely science projects." He acknowledged their potential to become real businesses but highlighted the compounded risks: "you’re making a bet on when robotics adoption happens, layered on top of a bet on whether it happens at all." Insight is "watching, but we’re not there yet." He playfully noted his son’s contrasting view, which he found typical of a 23-year-old.
The Perils of Concentration Risk and the Value of Diversification
With OpenAI and Anthropic reportedly absorbing roughly half of all VC dollars in the first half of the year, the issue of LP concentration risk is paramount. Parekh affirmed that Insight is "not overly concentrated," so it’s not an internal issue. However, as an LP in other funds, he revealed that some funds are pitching LPs by stating "35–40% of this fund is going into one of those two companies."
While not dismissing the potential success of OpenAI and Anthropic, Parekh cautioned against excessive concentration. "This business has always rewarded diversification over a long horizon," he stated, adding that as a firm on "fund 13," they must think in terms of "ten funds, not one." He acknowledged that in the current moment, heavy concentration might yield superior returns, but historical data does not support it. Most LPs, he believes, also prefer diversified exposure, though he recognized firms like Founders Fund and Thrive as exceptions that have successfully executed concentrated strategies.
Prioritizing Liquidity: The Importance of DPI
Parekh highlighted a significant challenge in the current market: "a lot of funds raised a lot of money and haven’t returned any of it to LPs." He predicted that many first- and second-time funds might struggle to raise subsequent funds due to their failure to prioritize liquidity. He advises fund managers: "if Anthropic’s going to triple from here, fine – take your basis out anyway. LPs want to know you can turn positions into cash; that’s the job."
He candidly admitted Insight’s own past missteps in this area, acknowledging that as major LPs in their own funds, they sometimes hesitated to sell, thinking, "’Why sell if it could double again?’ But LPs don’t get paid that way." Over the past two years, Insight has made a concerted effort, returning "more than $20 billion to LPs through strategic sales and IPOs, with a few billion more coming." He underscored that "DPI (Distributions to Paid-In Capital) matters, even on fund 13." Secondaries, he clarified, serve primarily as a liquidity mechanism, often benefiting early venture investors more than employees. He summarized the dilemma: "Nobody complains about a 10x that stays a 10x, but if it drops to 5x, people ask why you didn’t sell."
Advising Founders on Frothy Valuations
Referencing VC Elad Gill’s argument about a "narrow window" when a company’s valuation might be at its peak, Parekh confirmed that Insight constantly engages founders in this conversation, though he jokingly noted that "founders listen to me about as much as my kids do." He stressed that it’s a "case by case" decision, but when founders receive offers at "frothy valuation[s]," he challenges them to consider "what happens when the market corrects, because it will, even if I can’t tell you when." While he cannot time the market, his advice is to "de-risk 10 or 20%." He warned against the unsustainable nature of current valuation growth: "You can’t compound $40 billion at 50% every two months for two years without becoming the world economy. That math doesn’t work."
The Impact of AI IPOs and the Future Market
The anticipated public filings of Anthropic and OpenAI are set to be transformative for the industry. Parekh noted that Anthropic is "already larger than Salesforce and it’s four years old." He predicted that the simultaneous IPOs of "three companies – SpaceX, Anthropic, OpenAI – going public within six to eight months, each north of a trillion dollars in market cap," will set an unprecedented benchmark. He observed that the market absorbed SpaceX just fine. The critical question for him is "when the next tier of companies goes public, and what bar that sets." He mused that for public-market investors, "double, double, triple, triple" growth might not seem as exciting when compared to companies that scale from zero to $65 billion in four years. However, he acknowledged that "10x growth rate can’t continue forever," and eventually even these giants will become "normal-growth companies," necessitating public markets. He expects "more of these IPOs over the next 18 months."
The Inevitable Boom-Bust Cycle of Capital
Addressing whether the anticipated return of LP capital will sustain the current market frenzy, Parekh drew a parallel to personal investing behavior: "We all do this in our personal lives – stay out of an expensive market until we can’t stand it anymore, and pile in right when we should be pulling back." He sees LPs exhibiting the same "boom-bust cycle at a macro level," noting that after pulling back post-2021, "now the same LPs are piling back in." He highlighted the normalization of large funds, stating, "Venture-growth funds of $6 to $10 billion used to be rare; now they’re common."
Strategic Decisions: Doubling Down or Walking Away
Parekh explained that the decision to double down on an investment or walk away varies "enormously." He cited "Wonderful," an enterprise AI agent platform created less than two years ago, which saw Insight participate in two rounds, reaching a $5 billion valuation—a "very fast double-down." Conversely, some 2021 investments languished for "three or four years before finding product-market fit."
This dynamic is central to Insight’s portfolio reviews, where they recently scrutinized "300 portfolio companies over three days." The aim is to identify not just the major positions but also those "showing an inflection point worth doubling down on, buying secondary in, or in some cases pulling back from." He offered Armis, a security company, as a prime example of their strategic approach. Insight initially lost the deal to Sequoia but maintained a relationship with a small $5 million check from an $11 billion fund. Eighteen months later, they "bought out the entire cap table, including Sequoia, for a nine-figure check, and sold it to ServiceNow this year for $7 billion." This illustrates that success can come from both small and large checks, with the ultimate goal being "finding the best founders in the best markets."






