 11

Better Mortgage and Coinbase have officially expanded their innovative Bitcoin-backed mortgage product to be generally available across the United States. This groundbreaking offering empowers US homebuyers to leverage their Bitcoin holdings as collateral for a down payment without the necessity of selling their digital assets. The announcement, made by the companies on Wednesday, marks a significant step forward in the integration of cryptocurrencies into the traditional real estate sector.
Under the terms of this novel product, homebuyers can secure a Fannie Mae-backed home loan by pledging Bitcoin (BTC) as collateral for their down payment. According to information detailed in Coinbase’s Help Center, the product functions by pairing a standard home loan with a separate down payment loan that is secured by the borrower’s Bitcoin. A crucial requirement for borrowers is to pledge a value of BTC that is at least 250% of the down payment loan amount. Once pledged, the Bitcoin is transferred to Better Mortgage’s custodial account, which is managed on Coinbase Prime.
A key feature designed for borrower convenience is the synchronized repayment structure. Both the home loan and the down payment loan carry identical interest rates and amortization terms. Consequently, borrowers will manage these obligations through a single, consolidated monthly payment. The pledged Bitcoin remains under Better Mortgage’s custody until the mortgage is fully repaid or refinanced, at which point the collateral is returned to the borrower, subject to the specific terms and conditions of the loan agreement.
The product has been designed with a degree of flexibility to address the inherent volatility of cryptocurrency markets. Declines in the price of Bitcoin, on their own, will not trigger margin calls or necessitate any adjustments to the mortgage terms. However, a critical safeguard is in place: if a borrower becomes delinquent on their payments for 60 days, Better Mortgage reserves the right to liquidate the pledged Bitcoin to cover the outstanding debt, as outlined by Coinbase.
Eligibility for this Bitcoin-backed mortgage is subject to several criteria. Applicants must be US residents and possess a verified Coinbase account. Furthermore, all borrowers must still meet Better Mortgage’s established underwriting requirements, which include assessments of creditworthiness, income verification, and other standard financial evaluations. For existing Coinbase One members, there is an additional incentive: they are eligible for a 1% rebate from Better Mortgage, capped at $10,000, which can be applied towards closing costs and associated fees.
This nationwide rollout follows an initial announcement of the token-backed mortgage in March, when Better Mortgage and Coinbase first introduced the concept. At that time, the product was made available through an early-access program, allowing a select group of borrowers to test and provide feedback on the innovative financing solution.
The expansion of Bitcoin-backed home financing is occurring within a broader context of increasing efforts to incorporate digital assets into the US mortgage underwriting process. This trend is gaining momentum, signaling a potential shift in how the real estate industry views and utilizes alternative assets.
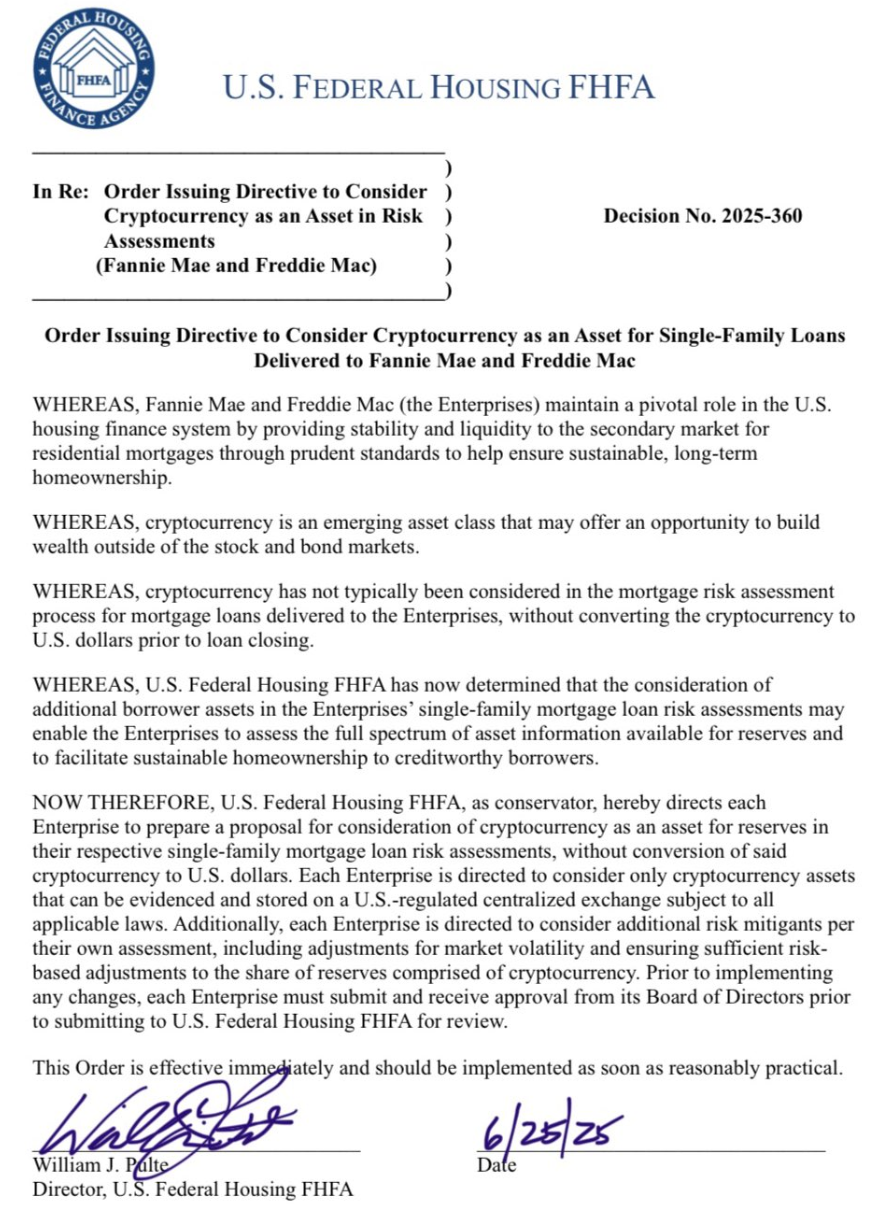
A significant development in this direction came in June 2025, when the Federal Housing Finance Agency (FHFA) issued a directive to Fannie Mae and Freddie Mac, two government-sponsored enterprises that play a crucial role in the secondary mortgage market. The FHFA mandated that these entities develop proposals to consider cryptocurrency held on US-regulated centralized exchanges as a valid asset in single-family mortgage risk assessments. Crucially, this directive specifies that such assessments should be conducted without requiring the conversion of cryptocurrency to US dollars.
The FHFA’s directive also stipulated that Fannie Mae and Freddie Mac must consider risk-mitigation measures to address the inherent volatility of cryptocurrencies. Any proposed changes to their policies or risk assessment frameworks stemming from this directive are required to be submitted to their respective boards for approval before undergoing review by the FHFA. This ensures a structured and regulated approach to integrating digital assets into the mortgage ecosystem.
Beyond the actions of the FHFA and its directed entities, other US lenders have also begun to embrace cryptocurrency in their mortgage operations. In January, Newrez, a prominent mortgage lender and servicer, announced its intention to recognize certain cryptocurrency holdings when evaluating mortgage applications. This policy, which commenced in February, extends to both home purchases and refinancing scenarios, further broadening the acceptance of digital assets within the lending landscape.
The increasing availability of Bitcoin-backed home financing comes at a time when US housing prices remain at historically elevated levels. Data compiled by the Federal Reserve Bank of St. Louis, drawing from the US Census Bureau and the Department of Housing and Urban Development, indicates that the median sales price of a new US home hovered around $400,000 in 2026. While median new home prices have seen some fluctuations since their peak in 2022, they continue to represent a significant financial commitment for prospective buyers.
This confluence of technological innovation, regulatory evolution, and market conditions suggests that digital assets are poised to play an increasingly significant role in the US housing market. The Better-Coinbase Bitcoin-backed mortgage product represents a tangible manifestation of this trend, offering a new pathway for individuals to achieve homeownership by harnessing the value of their digital wealth. As the industry continues to adapt, further integration of cryptocurrencies into mortgage underwriting and financing is likely to emerge, potentially reshaping traditional financial practices.






